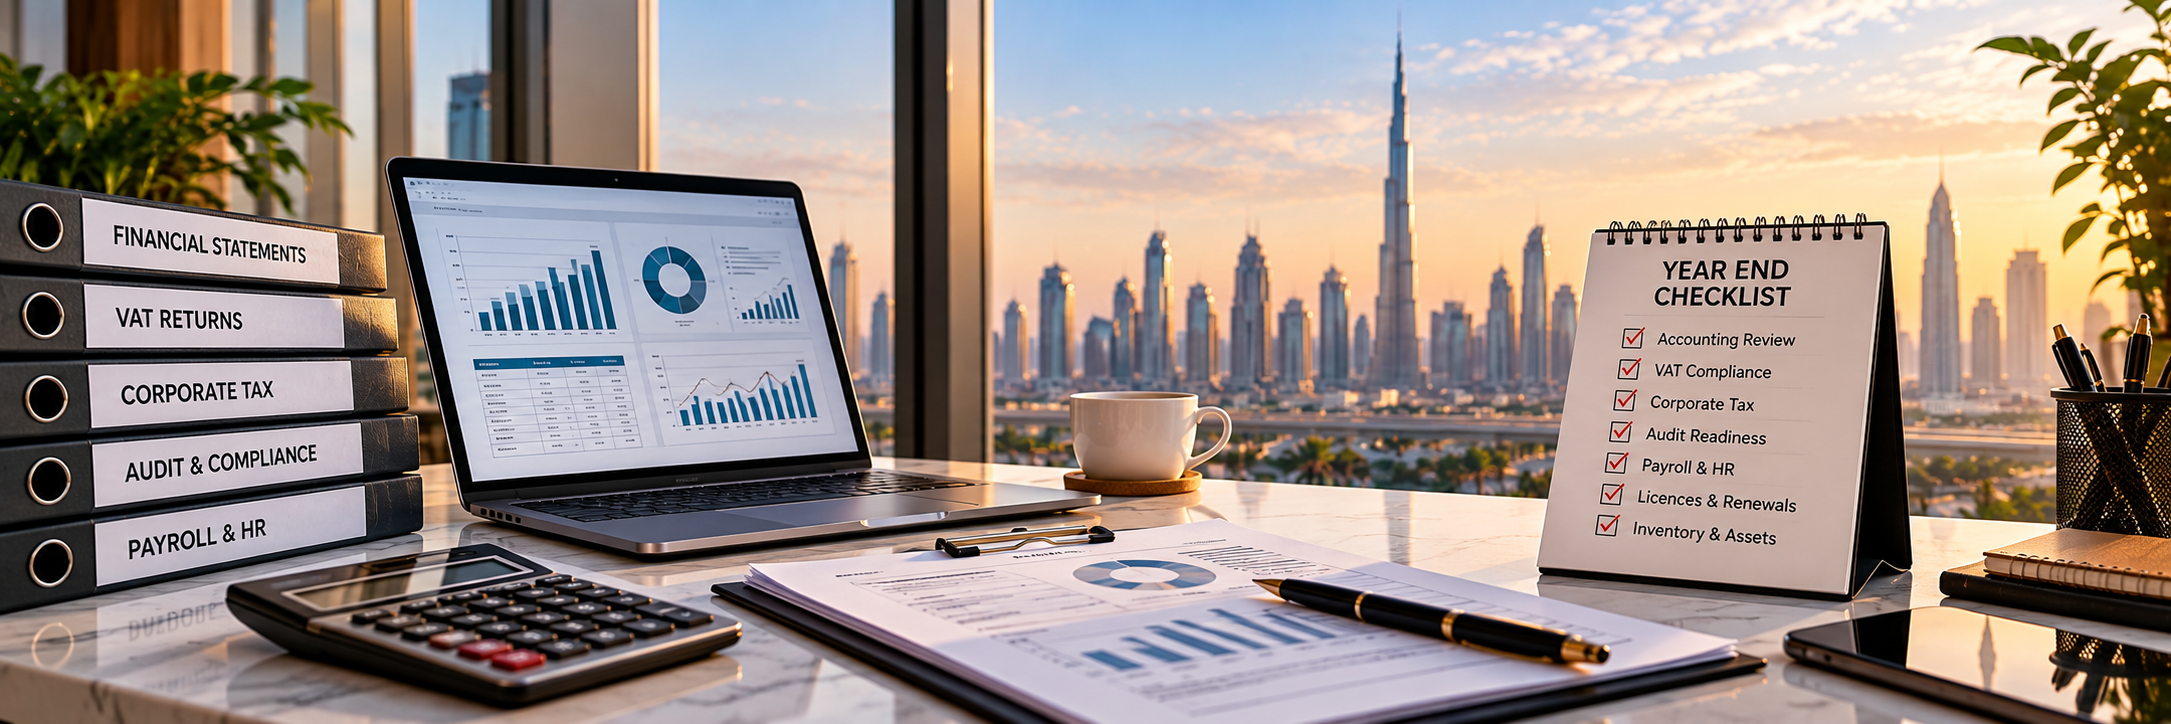
Quick answer: A thorough UAE year-end review covers financial statement preparation, bank reconciliations, accounts receivable and payable management, VAT reconciliations, corporate tax readiness, audit obligations, payroll and end-of-service accounting, compliance tracking, and physical verification of inventory and fixed assets where applicable. Getting ahead of these items keeps you compliant and makes financial reporting clean across all tax periods.
Table of Contents
- Why does year-end matter for UAE businesses?
- How do you review financial statements at year-end?
- How do you reconcile bank accounts and payments?
- How should receivables and payables be managed?
- What does year-end VAT compliance involve?
- How do you prepare for UAE corporate tax filing?
- How should you evaluate internal controls and audit requirements?
- What payroll records need checking?
- Which licences, permits, and insurance need reviewing?
- How should inventory and fixed assets be evaluated?
- 2026 Compliance Alert: UAE eInvoicing System
- Conclusion
- Frequently asked questions
As each financial year comes to a close, every UAE business, whether in a free zone or mainland, needs to take a close look at its books, taxes, and compliance. Year-end is not just about closing your accounts; it’s about preparing your business for stronger financial growth in the year ahead.
To help you stay compliant and organized, here’s a practical UAE year-end financial checklist that covers everything from accounting and VAT to corporate tax and growth planning, updated for the 2026 close and built to apply every year going forward.
UAE Year-End Financial Checklist 2026
Year-end is the time when all business-related matters like books of accounts, tax, and compliance are evaluated together. Usually, businesses treat it as a general administrative activity while neglecting that it needs a structured approach. Errors mostly happen due to this mistake. A VAT mismatch or an upcoming licence expiry may not seem pressing in isolation, but combined at year-end, they create unnecessary financial and operational exposure.
This list has been compiled in a logical sequence, progressing from core financial accounting to tax reconciliations, statutory reviews, and physical asset verification.
1. Review Your Financial Statements
Start by reviewing your company’s core financial statements, including the profit and loss statement, balance sheet, and cash flow reports. Financial statements serve as the primary accounting starting point for determining taxable income for UAE Corporate Tax.
Under UAE Corporate Tax rules, financial statements must generally be prepared in accordance with International Financial Reporting Standards (IFRS). However, eligible small businesses with annual revenue not exceeding AED 50 million may apply IFRS for SMEs.
Check for posting errors, unallocated transactions, or unbilled revenue. Ensuring your financial statements are accurate and fully compliant with applicable accounting standards guarantees readiness for corporate tax filings, bank credit reviews, and statutory audits.
2. Reconcile Bank Accounts and Payments
Before closing your ledger, confirm that every bank transaction matches your internal accounting records exactly. That means verifying incoming payments, outbound transfers, bank fees, interest charges, and credit card settlements, all of it.
For UAE businesses heading into year-end reporting, bank reconciliations are the practical check that catches unrecorded bank charges, missing vendor payments, and duplicate postings before they distort your final profit figures.
3. Manage Accounts Receivable and Payable
Effective year-end management of payables and receivables requires a detailed review of ledgers rather than attempting to clear all balances prior to period-end. A robust financial review includes:
- Performing accounts receivable ageing analysis and assessing debts for recoverability.
- Calculating and recording bad and doubtful debt provisions in line with relevant accounting principles.
- Reconciling vendor ledgers against official supplier statements to identify unrecorded invoices.
- Identifying accrued and unrecorded liabilities to ensure all expenses incurred in the period are accounted for.
- Verifying revenue and expense cut-offs to ensure transactions are reported in the correct financial period.
- Reconciling intercompany and related-party balances.
Addressing these items yields a true financial snapshot and prevents distorted earnings figures entering the new financial year.
4. Review Your VAT Compliance
VAT compliance in the UAE operates on distinct reporting cycles (monthly or quarterly) and is not bound to a company’s financial year-end. Consequently, year-end is not a mechanism to defer regular tax obligations or hold back error corrections.
When errors are identified, they must be addressed in accordance with Federal Tax Authority (FTA) regulations and Tax Procedures law. For instance, the FTA prescribes specific treatment based on whether an error results in a tax understatement exceeding AED 10,000, which requires a Voluntary Disclosure, compared to smaller adjustments that may be corrected on a subsequent tax return.
At year-end, businesses should conduct a full VAT reconciliation comparing the General Ledger (GL) sales and purchase accounts against filed VAT returns, underlying tax invoices, and output/input tax accounts to identify and rectify any accounting discrepancies under standard FTA protocols.
5. Prepare for UAE Corporate Tax Filing
Corporate tax is a key annual obligation for taxable entities in the UAE. As a general rule, Corporate Tax returns and corresponding tax payments are due within nine months following the end of the relevant Tax Period. For example, for a business with a financial year ending 31 December 2025, the corporate tax return and payment must be submitted by 30 September 2026.
Your corporate tax preparation should include confirming your active tax registration status, calculating taxable income from audited or IFRS-compliant financial statements, applying eligible adjustments, and assembling supporting documentation.
For Free Zone entities claiming Qualifying Free Zone Person (QFZP) status, 0% tax treatment is not a one-time approval that carries forward automatically. A Free Zone Person must meet all qualifying criteria continuously throughout each Tax Period, including maintaining adequate substance, earning Qualifying Income, complying with transfer pricing rules, and meeting mandatory audit requirements. Failing to meet any condition during a Tax Period invalidates QFZP status for that entire period.
6. Review Internal Controls and Audit Requirements
It is important to distinguish between internal audit activities and statutory audits of financial statements, as they fulfill different functions and legal requirements:
- Statutory Audited Financial Statements: Mandatory for specific entities by law. Under Ministerial Decision No. 84 of 2025, audited financial statements are mandatory for Qualifying Free Zone Persons claiming the 0% rate regardless of revenue, as well as for taxable persons with annual revenue exceeding the threshold prescribed by law (such as AED 50 million).
- Internal Control Reviews: Voluntary evaluations of internal processes, risk management, authorization limits, and operational controls. Conducting regular internal control reviews helps identify procedural weaknesses, prevent fraud, and simplify the external statutory audit process.
7. Check Employee and Payroll Records
Payroll accounting requires thorough validation at year-end. Establishments registered with the Ministry of Human Resources and Emiratisation (MoHRE) must ensure full compliance with the Wage Protection System (WPS), subject to statutory exceptions, while entities operating in independent financial free zones like DIFC or ADGM must comply with their respective employment regulations.
Alongside verifying basic salary and bonus payments, year-end payroll accounting should cover:
- Calculating accrued annual leave liabilities.
- Reconciling End-of-Service Gratuity (EOSG) or workplace savings scheme contributions (e.g., DEWS where applicable).
- Reconciling outstanding employee loans or salary advances.
- Verifying expense reimbursements.
- Performing a comprehensive payroll-to-General-Ledger reconciliation.
8. Review Licences, Permits, and Insurance
Commercial trade licences, visas, office leases, and corporate insurance policies carry specific validity periods that do not automatically align with a company’s financial year-end.
Instead of assuming renewals must occur before December 31st, use the year-end period to audit all corporate documentation and establish a tracking schedule for upcoming renewals due in the next 3 to 6 months. This proactive check helps avoid late penalties, regulatory suspensions, or lapse in statutory insurance coverage.
9. Evaluate Inventory and Fixed Assets
For businesses that carry physical stock, a complete physical inventory count must be conducted at or near the year-end date. Counted physical quantities must be reconciled against accounting records, with adjustments made for damaged, slow-moving, or obsolete inventory.
For fixed assets, businesses should perform physical verification to confirm asset existence and condition. Review the fixed asset register to reflect new additions, disposals, useful lives, and impairment losses. Note that UAE Corporate Tax calculations start from accounting net profit determined under recognized accounting standards (such as IFRS), making proper accounting depreciation and asset records essential for tax compliance.
2026 Compliance Alert: UAE eInvoicing System
As part of your 2026 year-end financial and IT planning, businesses must prepare for the upcoming mandatory UAE eInvoicing System (E-Invoicing Framework).
For phase-one businesses meeting the applicable revenue threshold (such as AED 50 million or more), the official timeline requires appointing an Accredited Service Provider (ASP) by 30 October 2026, ahead of mandatory transaction reporting going live from 1 January 2027. Reviewing accounting software capabilities and data structures during your 2026 year-end check ensures a smooth transition to compliant structured electronic invoicing.
Conclusion
Completing your UAE year-end financial checklist ensures your business stays compliant, organized, and positioned for sustainable growth. From maintaining accurate accounting records to fulfilling evolving tax duties, systematic year-end reviews protect your business from regulatory penalties and operational friction.
If you require professional support with corporate tax, statutory accounting, VAT reconciliations, or audit readiness in the UAE, Smart Zone Tax & Accounting (SZTA) is available to support your team. Our qualified tax and accounting specialists deliver precise, compliant, and stress-free year-end financial management.
Get in touch with Smart Zone Tax & Accounting (SZTA) today:
- Call Us: +971 52 659 4451
- Email Us: info@smartzone.ae
- Visit: smartzone.ae